123 Maple St, Cary, NC 27519
A solid, improving-district home with real upside — but a recent addition and an unconfirmed HOA both need paperwork before you offer.
Data coverage
How much source data we found for each section — not a risk rating. Read every section before you offer.
Buyer score
123 Maple St is a well-located, 1998-built home in a Cary neighborhood with genuinely strong momentum — rising home values, an improving school district, and minimal flood risk. The 11 permits on record suggest active upkeep, but a recent addition needs its final inspection confirmed, and HOA details remain entirely unverified. The single most important thing to investigate before making an offer is getting paperwork on both the addition and the HOA directly from the seller.
The score weighs flood risk, schools, the neighbourhood, the property's age and condition, and value. It's where to start, not a verdict — nothing here replaces an inspection.
Flood
20%
9/10
Schools
25%
8/10
Neighborhood
20%
7/10
Property
20%
6/10
Value
15%
6/10
Positives
Zone X flood risk with no federal insurance requirement for a government-backed mortgage
School district per-pupil spending up 28% since 2019, well above the metro average
Neighborhood home values up 22% over 5 years with rising income and low unemployment
Risks & Unknowns
11 permits on record including what appears to be a recent addition — final inspection status is unconfirmed
Records indicate a possible HOA, but this is a data-provider signal, not verification — fees and rules are unknown
Walk Score of 41 means daily errands require a car, which can narrow the resale buyer pool
Resale Outlook
Strong resale fundamentals — rising neighborhood values, an improving school district, and low flood risk all support long-term appreciation, though car-dependency is a modest headwind versus more walkable Cary neighborhoods.
/10
What no single listing tells you
Facts across different data layers, read together
Permit records show 11 filings including what appears to be a recent addition, with final inspection status unconfirmed (property layer)
Records indicate a possible HOA in a Cary community, but fees and rules are entirely unverified (HOA layer)
Both open questions point the same direction: get the seller to produce paperwork — the addition's certificate of occupancy and the HOA's disclosure package — before you write an offer, not after.
Questions to send the agent
Can you confirm the addition shown in Wake County permit records received a final inspection and certificate of occupancy?
to verify the added square footage was legally completed
Is there an active HOA for this property, and if so, can you provide current dues, the reserve fund study, and any pending special assessments?
to confirm HOA existence and assess financial health before committing to ongoing fees
Documents to request
If you put down
At this price, a 3.5%-down loan would exceed FHA's limit here (about $541,287 for a single-family home), so FHA financing is unlikely to be available — a lender can confirm.
Conventional PMI cancels automatically at 78% loan-to-value, and can be requested at 80%. On schedule that's about 12 years in, assuming no extra principal and no change in value.
Cash you'd need at closing
$48,048 – $66,408
$30,600 down, plus 2–5% closing costs and prepaid taxes/insurance for the escrow account.
Based on an estimated value of $612,000 at a 7.10% 30-year fixed rate. Property tax is the current bill on county records — your first bill after closing may differ. Insurance is estimated and excludes flood coverage. HOA dues are not included — verify with the seller. Closing costs and cash to close are estimates; your lender's Loan Estimate is the real number.
Every figure here is derived from an estimated value of $612,000, not a list price or your offer — the shape holds, the exact numbers move with what you actually pay.
⚠ HOA fees not included — Cary HOAs often run $100–$400/mo. Request the fee schedule before making an offer.
Flood Zone
X
Federally Mandated Insurance
Generally Not Required
Federal rules only — a lender can still choose to require flood insurance on this zone. Ask before assuming you won't need it.
Zone Description
Minimal flood hazard — less than 0.2% annual chance of flooding.
5 paid NFIP flood claims in this ZIP code since 2000 — worth asking about even outside a high-risk zone.
This is a county-level EPA prediction, not a measurement of this specific home — radon levels vary house to house based on soil conditions, foundation type and ventilation. A radon test (inexpensive, DIY kits available) is the only way to know this home's actual level; the EPA recommends testing every home regardless of zone.
Median Income
$118K
Income Growth (5yr)
+18.0%
Median Home Value (ZIP)
$462K
Price / Sq Ft (Metro)
$227
Unemployment Rate
4.2%
Price Growth (Metro, per yr)
+4.1%
Walk Score
Car-Dependent
Transit Score
Bike Score
ZIP home values (Census survey, 2014–2018 vs 2019–2023): +22.0%. An older, slower-moving measure than the metro figure above.
Metro Price / Sq Ft Trend (5yr, Parcl Labs)
| Address | Price | Sqft | $/sqft |
|---|---|---|---|
| This home | $612,000 est. | 2,340 | — |
| 211 Weldon Ridge DrMar 2026 | $598,000 | 2,280 | $262 |
| 108 Grendon PlJun 2026 | $629,000 | 2,410 | $261 |
| 96 Bridle Boast RdJan 2026 | $512,000 | 1,980 | $259 |
Most similar in size first. Recorded sales near this address, not an appraisal — condition, lot, and finish level can all differ from this property.
Harris Teeter
0.8 mi · ★4.4
22 min walk · 4 min drive
Cary Family Medicine
1.4 mi · ★4.1
31 min walk · 5 min drive
+1 more within 1 mi
Bond Park
0.4 mi · ★4.7
9 min walk · 2 min drive
+1 more within 1 mi
Cary KinderCare
0.9 mi · ★4
19 min walk · 4 min drive
CVS Pharmacy
0.6 mi · ★3.9
13 min walk · 3 min drive
+1 more within 1 mi
Chick-fil-A
0.3 mi · ★4.5
7 min walk · 2 min drive
+7 more within 1 mi
Starbucks
0.5 mi · ★4.3
11 min walk · 3 min drive
+2 more within 1 mi
Planet Fitness
1.1 mi · ★4.2
24 min walk · 4 min drive
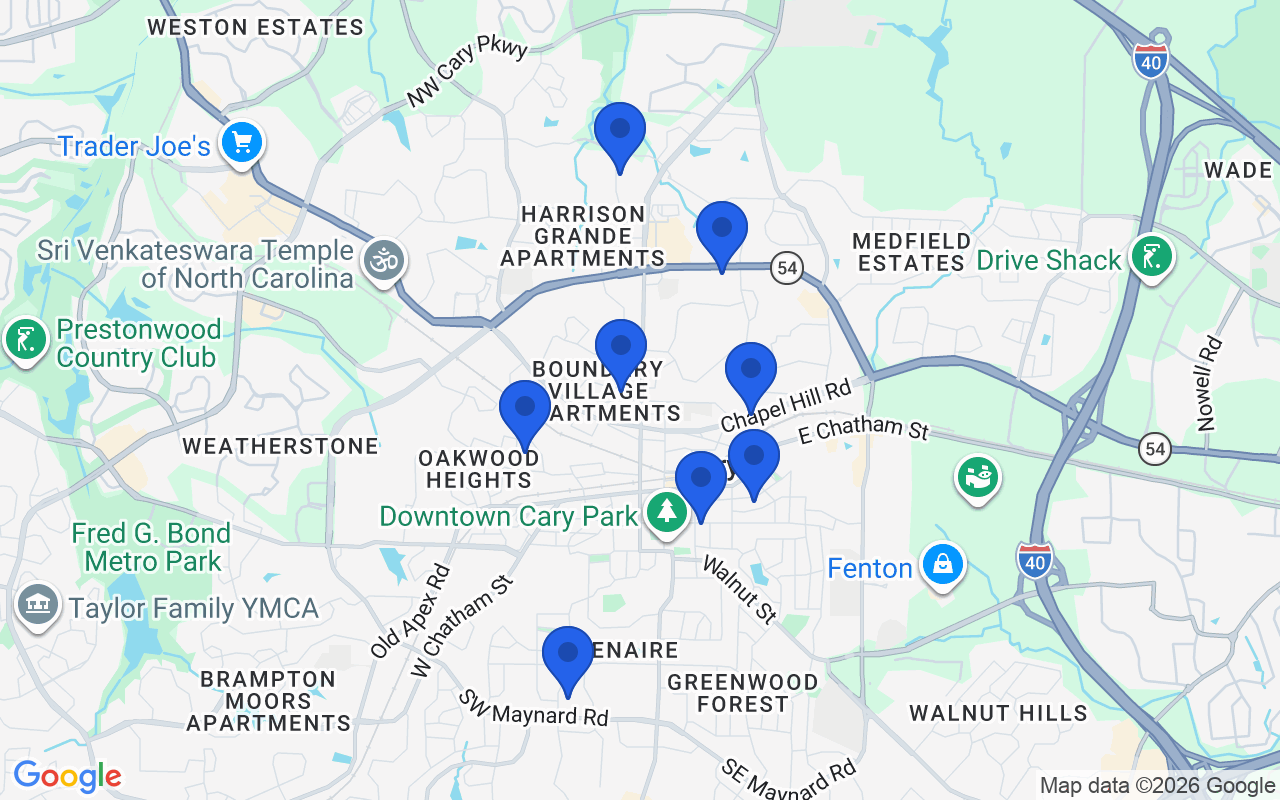
This score measures straight-line distance to nearby amenities, not walkability — it's not the same measurement as Walk Score in the Neighborhood section. A place can score well here and still require a car to reach those amenities safely on foot.
Explore all nearby amenities on Google Maps →
✓ Assigned schools confirmed via official district boundary data
Boundary confirmed for 2026-27. Grade letters above are the state’s own accountability rating (NC DPI), not GreatSchools/Niche — use the links below for those too.
School District
Wake County Public School System
Per-Pupil Spending
$11,200
Spending Growth (5yr)
+28.0%
Students per Teacher
14.8:1
Year Built
1998
Property Type
Single Family
Living Area
2,340 sqft
Lot Size
0.22 acres (9,583 sqft)
Bedrooms
4
Bathrooms
3
Floors
2
Price / sqft
$262
This property's estimated value works out to in line with recent similar-size sales nearby on a price-per-sqft basis.
Property Condition Risk
28 yr old homeRoof Risk
MediumHVAC Risk
MediumBuilt in 1998, the home is roughly 27–28 years old. Roofs typically last 20–25 years and HVAC systems 15–20 — both are at or past typical replacement age unless permit records confirm recent upgrades.
Roof Replacement (Est.)
$12K–$20K
HVAC Replacement (Est.)
$9K–$16K
Typical national ranges scaled to this home's square footage — not a quote. Get a licensed contractor's estimate for the real number.
Estimated Value (AVM)
Seller's Mortgage Balance
$367,000
Annual Property Tax
$4,890 / yr
Monthly Tax Cost
$408 / mo
Tax Status
✓ Current
Current Ownership
7 years
Ownership Type
Owner-Occupied
Recorded Sales
2 on record
Permit & Features
High permit count — pull the full permit history to confirm all work was properly permitted and closed.
Sales History
49% total appreciation over 8 years (6.2%/yr avg)
Tax History
+11% since 2024
Conventional / VA Loan Limit (County)
$832,750
This is the conventional loan limit. A veteran with full VA entitlement has no county limit at all — this figure only applies to conventional financing, or to VA borrowers without full entitlement.
This address sits inside an urbanized area, so it does not qualify for USDA 0%-down Rural Development financing.
This home's estimated value is above $495K, the sale-price limit for NC Home Advantage Mortgage and NC 1st Home Advantage Down Payment, so neither program is likely to apply unless it sells for less.
Before You Submit an Offer
6 items specific to this property
Must Verify
Recommended
Negotiation Leverage
If the addition permit is unclosed, use the cost of a compliance inspection as leverage for a price reduction or seller credit.
Rates have stayed elevated this year, so a rate buydown or closing-cost credit is a reasonable ask in this market — though it's a general market condition, not something specific to this house.
UnveilHome aggregates publicly available data for informational purposes only. This is not legal, financial, or real estate advice. Always consult qualified professionals before making property decisions.